The short version
- Homeowners pick a roofer on trust. Your Google Business Profile, your reviews and a website that shows your license number and real jobs do more of the selling than any slogan.
- Southwest Florida roofing demand is driven by storms, insurance letters and aging roofs. Plain-English pages that answer those situations bring in buyers who are ready to move.
- Florida law puts real limits on how roofers can advertise around insurance claims. Know the rules before storm season, not after.
- Paid ads work best once the basics are in place, and only if someone answers the phone fast. A missed call in the week after a storm is usually a lost job.
Roofing in Southwest Florida doesn’t run on a normal sales calendar. A quiet month can turn into a flood of calls overnight after a named storm. Every one of those buyers is nervous. A roof is a big check, and after Hurricane Ian in 2022 and the storms that followed, most people in Lee and Charlotte counties have heard a story about a roofer who took a deposit and disappeared. That’s why roofing marketing here is mostly about one thing: proving you’re the real, licensed, local company before the homeowner ever calls.
This playbook walks through the pieces that matter, in the order we’d tackle them if we were running a roofing company between Naples and Sarasota.
Know why homeowners are calling
Most Southwest Florida roofing calls come from one of a few situations:
- Storm damage. These buyers want someone fast and trustworthy.
- An insurance letter. The carrier wants an inspection or a replacement before it will renew. These buyers are confused and on a deadline.
- An old roof and a leak. The classic replacement job, where buyers compare two or three companies.
- Buying or selling a home. The inspection flagged the roof and everyone wants a quote quickly.
Each one needs a different message, and your marketing should speak to each directly.
Step 1: Get your Google Business Profile right
For “roofer near me” and “roof repair Cape Coral” searches, the map results at the top of Google usually get the first look. That’s your Google Business Profile. For most roofing companies it’s the single most valuable piece of free marketing they have.
- Choose Roofing contractor as your primary category.
- Set your service area to the places you actually serve. With no walk-in customers, hide the address. Our guide to local SEO for service-area businesses explains how.
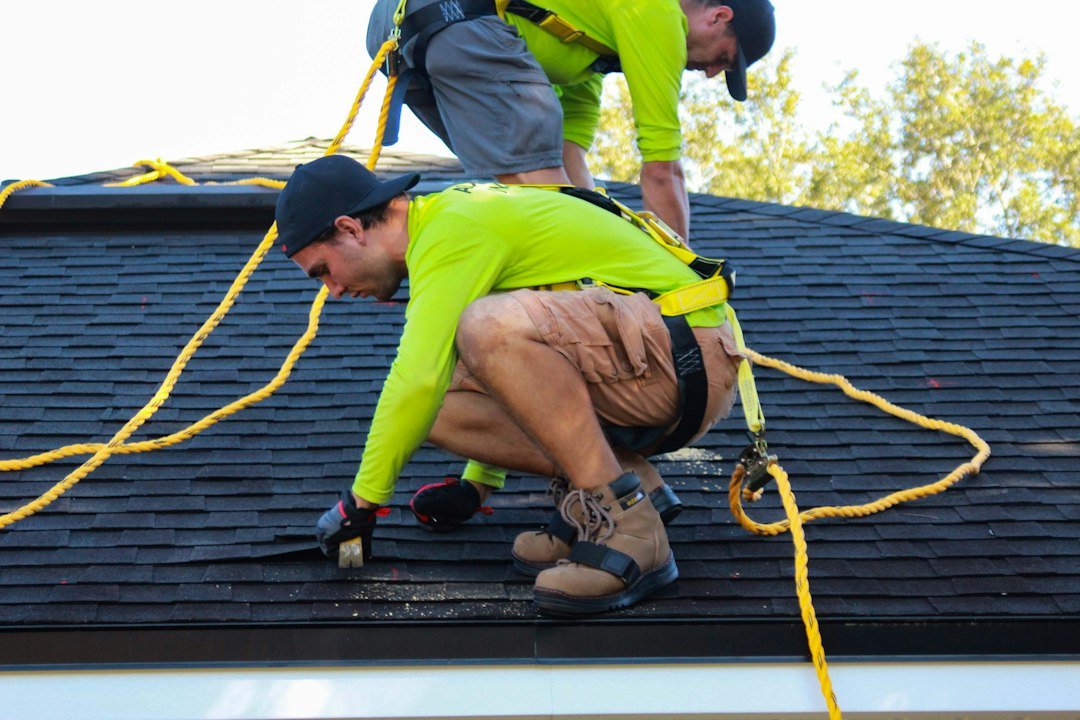
- Add real job photos regularly: tear-offs, dry-in, finished roofs, your crew and trucks.
- List each service (replacement, tile, metal, flat roofs, repairs, inspections).
If your profile has never been set up properly, start with our Google Business Profile setup guide.
Step 2: Build a review engine before the next storm
Reviews are where a nervous homeowner goes to decide whether you’re legit. The time to build them is during the steady months, not the week after a hurricane when every roofer in the state is in town.
Ask every happy customer at the end of the job and text a direct review link the same day. Reply to negative reviews calmly and with facts; our article on responding to bad Google reviews has templates.
How many do you need? There’s no magic number, and it depends on your competition. Our breakdown of how many Google reviews it takes to rank locally shows how to size it up in your own market. If keeping up with your profile and reviews is falling through the cracks, a team that handles Google profile management, local SEO and reviews can keep it moving every week.
Step 3: Make your website prove you’re the real deal
Most homeowners check your website before they call, even when they were referred. They’re looking for signs you’re established.
Put your license number where people can see it
Florida law already requires it. Under section 489.119 of the Florida Statutes, a contractor’s certification or registration number has to appear in offers of services, bids, contracts and advertisements, as defined by the licensing board’s rules. Putting it in your site header or footer covers you and doubles as a trust signal, because buyers can look it up on the state’s license lookup in about a minute.
Cover the basics buyers look for
- One page per roof type (shingle, tile, metal, flat) with photos from your own jobs.
- Your process from inspection and written estimate through permitting, tear-off, installation and final inspection.
- The cities and counties you serve.
- Tap-to-call and a short form on every page, because many roof searches happen on a phone in the driveway.
Step 4: Answer the questions SWFL homeowners are actually asking
Homeowners here have confusing questions tied to Florida law and insurance. A clear page on each one brings in people who are close to hiring. Two examples:
“My insurance company says my roof is too old”
Florida’s roof-age rules are a common source of confusion. Under section 627.7011, an insurer can’t refuse to issue or renew a homeowner’s policy solely because of the age of a roof that is less than 15 years old. For roofs 15 years or older, the insurer has to let the homeowner get an inspection by an authorized inspector, at the homeowner’s expense, before requiring replacement. And if that inspection shows at least five years of useful life left, the insurer can’t refuse coverage solely because of the roof’s age.
A homeowner who just got a nonrenewal notice wants that explained in plain English, and wants to know whether you do roof inspections. That’s a perfect page for your site.
“Do I have to replace the whole roof if only part is damaged?”
For years, Florida’s building code was read to mean that repairing more than 25% of a roof could trigger a full replacement. A 2022 law changed that for newer roofs. Under section 553.884, when a roof was built, repaired or replaced under the 2007 Florida Building Code or later, only the portion being repaired, replaced or recovered has to meet the current code. Older roofs may still fall under the old rule.
When you write about these topics, keep it factual, link to the statute, and tell readers to check with their insurance agent or attorney about their own policy. Don’t interpret a specific homeowner’s coverage. As you’ll see next, Florida law doesn’t allow contractors to do that unless they’re licensed public adjusters.
Step 5: Know the storm-season advertising rules
After a storm, it’s tempting to blanket neighborhoods with door hangers and flyers. Florida has specific rules about how contractors can market roof work tied to insurance claims, in section 489.147. In short, a contractor may not:
- Offer a homeowner a rebate, gift, gift card, cash, coupon, waiver of an insurance deductible or anything else of value in exchange for letting you inspect the roof or for making an insurance claim for roof damage.
- Pay or accept referral fees for work paid for by property insurance, apart from payment for the roofing work itself.
- Interpret policy language, advise on coverage, or adjust a claim on the homeowner’s behalf without a public adjuster license.
- Hand over a repair agreement without a good-faith, itemized estimate.
Roof-claim advertising, including door hangers, business cards, magnets, flyers, pamphlets and emails, also has to carry specific disclosures in at least 12-point type and at least half the size of the largest font on the piece:
| Required disclosure | What it tells the homeowner |
|---|---|
| The consumer is responsible for paying any insurance deductible | You won’t make the deductible go away |
| Knowingly waiving or rebating a deductible is a felony of the third degree | Deductible “deals” are illegal |
| Intentionally filing a claim with false, incomplete or misleading information is a felony of the third degree | Padding a claim is a crime |
Violations can bring discipline and fines of up to $10,000 per violation, and the law counts the actions of people soliciting on your behalf, including paid door knockers, as your own. Have your attorney look over any storm-season flyer or door hanger before it goes to print. Done right, a clean, compliant piece of marketing sets you apart from the storm chasers.
Step 6: Add paid ads once the foundation is solid
Ads work best once your profile, reviews and website are in good shape, because every ad click ends up checking those anyway.
| Channel | What it’s good for | Watch out for |
|---|---|---|
| Google Local Services Ads | Appearing at the very top of results for roofing searches, with leads billed per lead rather than per click | Google verifies your license and insurance, plus background checks where required; your reviews and responsiveness matter a lot |
| Google Search ads | Targeting specific searches like “tile roof replacement” or “roof inspection for insurance” | Clicks can get expensive; send them to a matching service page, not your home page |
| Facebook and Instagram ads | Showing finished roofs to homeowners in specific ZIP codes; reminding past site visitors about you | People aren’t searching for a roofer when they scroll; expect longer follow-up |
One thing to know about Local Services Ads: in October 2025 Google retired the “Google Guaranteed” badge and its money-back guarantee, and replaced it with a single “Google Verified” badge. If your website, truck wraps or ads still say “Google Guaranteed,” it’s time to update them.
For a deeper comparison of the two big platforms, read Google Ads vs. Facebook Ads for contractors. If you’d rather have someone build and run campaigns for you, Roll The Six manages Meta ad campaigns for local service businesses.
Step 7: Answer fast, follow up longer
None of the above matters if the phone rings out. After a storm, homeowners often call several roofers and go with whoever calls back first. Set up an automatic text-back for missed calls, answer web forms within minutes, and follow up on every unsigned estimate more than once.
If your team is on roofs all day and nobody’s watching the phone, a system for automatic lead follow-up can cover the gap. And it’s worth having your own storm plan for the office too. Our hurricane season business checklist covers the basics.
Roofing marketing checklist
- ☐ Google Business Profile claimed, primary category set to Roofing contractor, service area accurate
- ☐ New job photos on your profile every month
- ☐ A same-day review request after every job, and every review answered
- ☐ License number on your website, trucks, estimates, contracts and ads
- ☐ Separate website pages for shingle, tile, metal and flat roofs, with your own photos
- ☐ A plain-English page on roof inspections and insurance roof-age questions
- ☐ Storm-season flyers and door hangers reviewed by your attorney for section 489.147 disclosures
- ☐ No “Google Guaranteed” wording left anywhere
- ☐ Missed-call text-back turned on
- ☐ A follow-up routine for every open estimate
- ☐ Ads running only after the steps above are done, sent to matching service pages
The bottom line
The roofing companies that last in Southwest Florida aren’t the loudest after a storm. They’re the ones a nervous homeowner can check out in five minutes and trust. Build that proof in the quiet months, follow Florida’s rules when storms come, and answer the phone.
This article is general information, not legal advice. Laws change, so check the current statutes and talk with your attorney before relying on them for your business.